Mako Loans · Case study
From first click to submitted application.
Connecting brand, marketing, and borrower intake for an established lender.
Hard money lender, Albany NY · Lending across NY and Western MA since 2006
Explore the results
- Brand identity
- Website & SEO
- CRM and borrower intake
- Lead tracking & attribution
- Phone infrastructure
- Paid media
- Live reporting
The challenge
Where this started
Mako Loans brought an established lending business to the project, with more than 1,200 deals funded since 2006 across New York and Western Massachusetts.
The opportunity was to give that experience a consistent expression across its brand and marketing. Mako already had a website, Google Ads landing pages, and Facebook advertising. The next step was a unified visual identity and a more connected path from those channels to borrower intake.
We brought inquiries, follow-up, phone activity, and application tracking into one system configured around Mako’s lending process. Connecting those touchpoints would give the team a clearer view of how prospective borrowers moved from an initial inquiry to a submitted application.
Speed and trust matter to hard money borrowers. The project focused on helping prospective borrowers recognize Mako’s experience, understand its loan options, and take the next step, while giving the team consistent tools for intake and follow-up.
The build
Track the whole funnel.
- 01First clickCapture the source
- 02Lead capturedConnect calls, forms, and follow-up
- 03Application submittedSend the outcome back to the ads
Form submissions, calls, and inquiry volume show how advertising generates interest. We track each alongside the next step in the borrower journey: a submitted application.
In lending, an inquiry and a completed application represent different stages of a decision. An application includes property, deal, and financial information, giving the team more detail to evaluate the opportunity. Measuring both stages helps Mako understand inquiry volume and how that interest develops.
We built the tracking around Mako’s intake process, connecting lead and application activity in one view.
Leads and applications are tracked as separate conversion events with different values, with a higher value assigned to a submitted application. Both are sent back to Google Ads as offline conversions sourced directly from the CRM, giving campaign optimization information about inquiry volume and application activity.
Attribution uses native source data to carry each lead’s recorded origin from the first click through to the underwriting file, reducing manual tagging. Mako’s existing phone numbers were ported into the CRM platform, where call and voicemail transcripts are attached to the contact record so the team can review conversations alongside other borrower activity.
The team can see cost per lead, cost per application, and the rate at which leads become applications, broken out by channel and refreshed daily.
Mako can review inquiry volume and submitted applications together, with costs and conversion rates by channel, every morning.
The results
More leads. More applications.
Less spend.
Across the trailing twelve months, roughly four in ten leads go on to submit a full application, including property and financial information. Initial inquiries and completed applications remain separate measures in the reporting.
In the most recent reporting period, compared with the period before it:
- Paid leads
- +27%
- Applications
- +12%
- Cost per lead
- −26%
- Ad spend
- −6%
The period recorded more paid leads and submitted applications alongside lower ad spend and a lower cost per lead.
Consistent tracking also gives Mako a basis for comparing channel performance. In that same reporting period, paid social leads converted to submitted applications at a 48% rate versus 28% on paid search, with applications from paid social costing roughly 37% less. The team can use these measures together when reviewing channel mix and budget allocation.
Same reporting period · Submitted loan applications
Built to work together
The rest of the system
Brand identity
We developed a visual identity to reflect Mako’s established lending experience: a logo, color palette, typography, and guidelines for consistent use. The identity carries across the website, advertising, borrower-facing documents, and internal materials, creating a recognizable presence throughout the borrower relationship.
The website
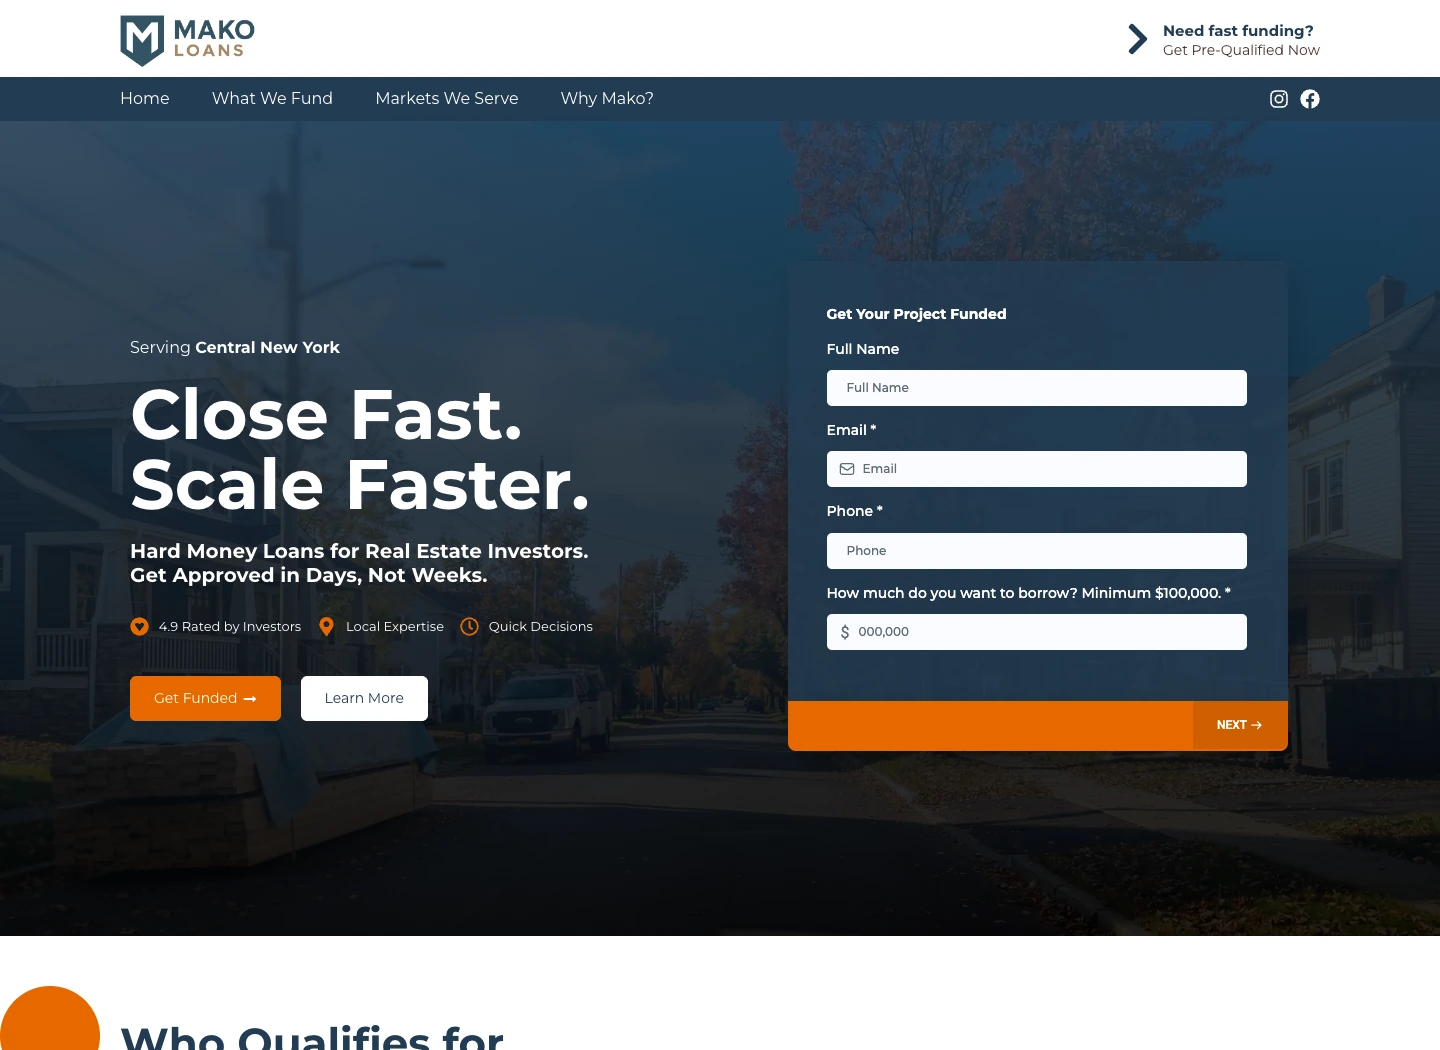
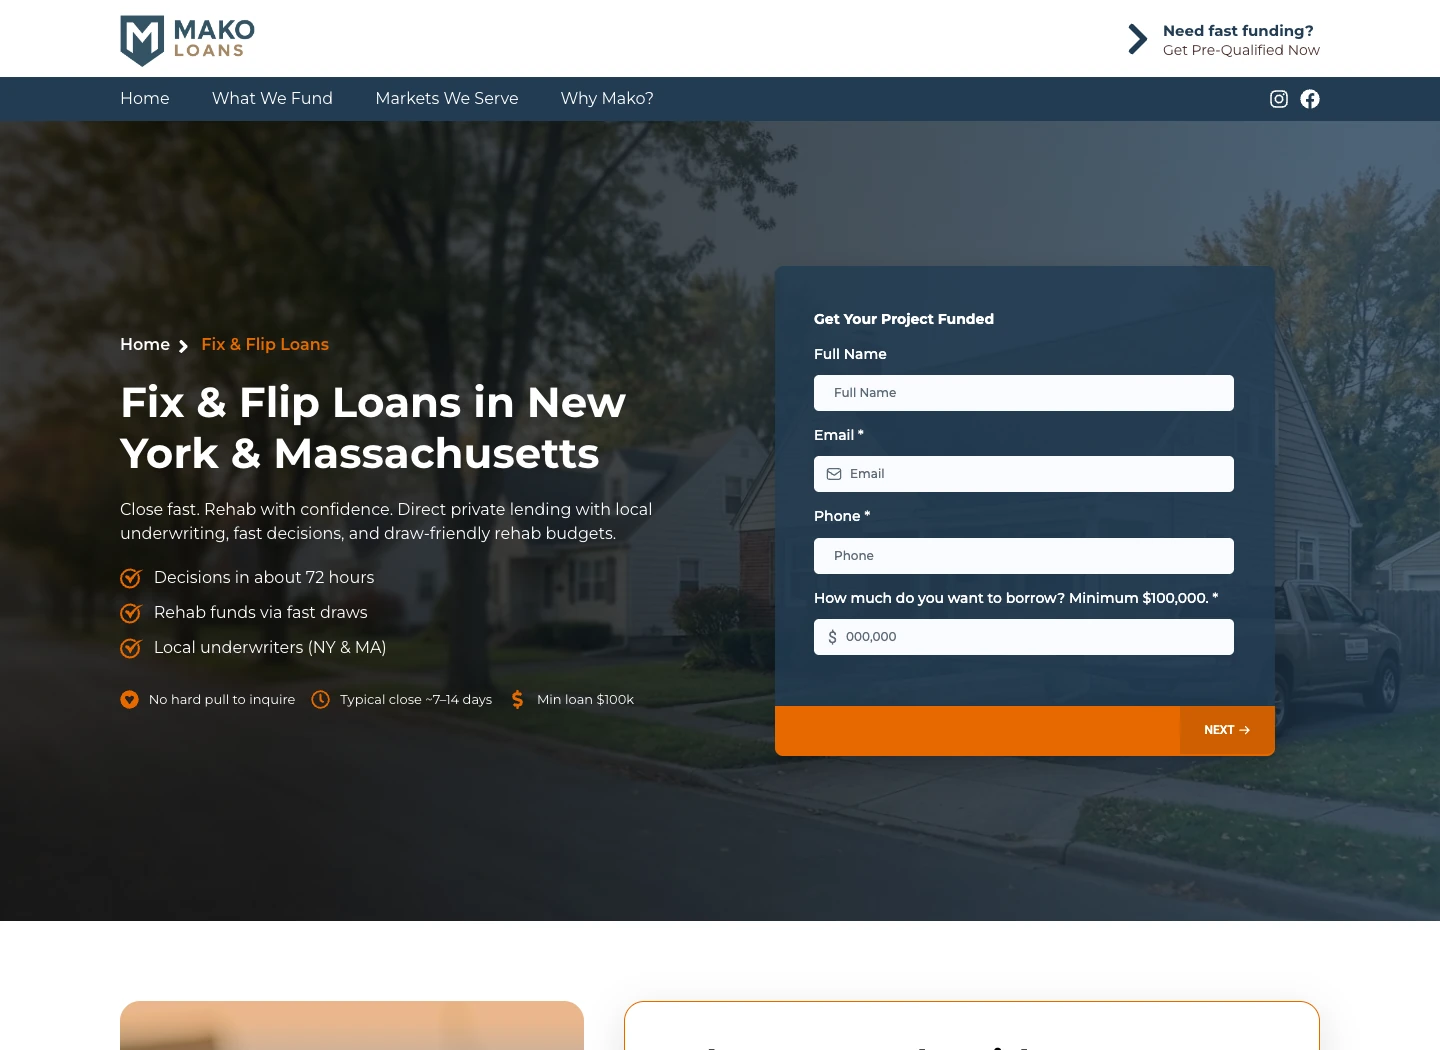
Mako’s website organizes its offerings around the loans and markets borrowers search for. Dedicated pages cover commercial bridge, fix & flip, BRRRR, rehab, new construction, and investment property loans, supported by location pages for the Capital Region, Hudson Valley, Central NY, Western NY, and the Berkshires. Paid campaigns direct visitors to relevant landing pages with a clear path to inquire.
CRM and borrower intake
Inquiries from paid campaigns, organic traffic, forms, and phone calls come into Scoutflow CRM configured around Mako’s workflow. A structured intake survey captures the property, deal, and sponsor details, followed by sequences that support borrowers as they prepare an application. Loan files sync automatically to Dropbox so underwriting, servicing, and outside attorneys can work from the same documents.
Follow-up supports borrowers whose timing extends beyond an initial inquiry. Roughly six in ten leads from a given reporting period remain in active follow-up after that period closes, with applications continuing to arrive in the weeks that follow.
Phone infrastructure
Nineteen numbers ported and hosted inside the same platform as the CRM. A custom phone tree routes callers by function and by territory — borrower servicing, payments and accounting, and the right regional lender for each market. Calls and voicemails are transcribed and attached to the contact record.
Paid media
Google Search and Meta campaigns cover Mako’s lending footprint, with structured ad copy testing, keyword and negative keyword management, and geographic budget control. Creative is developed around Mako’s lending criteria and underwriting-supported claims.
Live reporting
A custom dashboard brings CRM, Google Ads, Meta Ads, and Google Analytics data into one view for marketing attribution inside Mako’s CRM. It refreshes every morning and exports to PDF for sharing. A written monthly analysis adds context to the figures and supports planning for the next period.
Explore LendingHub, the investor portal built around Mako’s capital management workflow
Start with a conversation
This is for you if
You have an established business and want a clearer connection between marketing activity and the inquiries, applications, or customers it produces. Bringing your website, advertising, calls, and CRM together can help your team see the full journey and coordinate follow-up. We build around your team’s expertise and existing processes, connecting the tools and reporting that support the next stage of your business.
We’ll discuss the fit, scope, and costs before work begins.
Step 1 of 2 · Your business
Where should we start?
Choose a priority to continue.